
LYG (LYG) implied move — live earnings data
LYG (LYG) reports on October 29, 2026 (before market open). LYG's options are too thinly traded right now for a reliable implied move, so none is shown; the figure appears here as soon as the straddle has a dependable price, usually in the last sessions before the report. The implied move — also called the expected move — is derived from live options prices. Below, each report's implied move is compared with what LYG actually did on earnings day.
Updated October 27, 2026 · refreshed daily from live options data · methodology
- LYG (LYG) has moved ±2.6% on average at the peak of earnings day over the last 10 years (7 reports).
- LYG's actual earnings move exceeded the options-implied move in 0 of its last 1 reports (0%).
- On its last report (May 1, 2025) LYG options had priced ±4.5% and the stock closed -0.3%.
- Simulator — likelihood of success and risk/reward for the exact straddle, strangle or spread you'd put on, against LYG's own 10-year reaction record
- IV Rush Radar — LYG's live IV curve vs its typical pre-earnings ramp, with the three snapshot signals and the projected straddle
- DriftLab — LYG's follow-through, gap-fill and drift scores for the days after the print
LYG implied vs actual earnings moves
Each report: what options priced in beforehand (purple) vs the actual peak intraday move (green when it beat implied, grey when it stayed inside).
LYG beyond the implied move
The implied move is the size of the move. Three more readings for LYG, from the same pipeline — the free summary here, the full tools for members.
How LYG's earnings moves are distributed
| Percentile | 5th | 20th | Median | 80th | 95th |
|---|---|---|---|---|---|
| Move size | ±1.3% | ±1.6% | ±2.1% | ±2.5% | ±6.5% |
Recent regime: the 2-year average move (±2.7%) is hotter than the 10-year average (±2.6%).
What LYG does after the print
The implied move above is the size options price for the report. How the move unfolds afterwards is a separate question, and DriftLab tracks it for LYG across every past report: the follow-through score (does the earnings-day direction continue or reverse?), the gap-fill probability (how often the opening gap gets filled), the PEAD score (post-earnings drift strength), the reaction path of every release out to sixty sessions, and the current run drawn against the projected drift into the next report. One reading to set expectations: in 3 of LYG's last 7 reports the stock was further in the direction of its earnings-day close thirty sessions later. The scores themselves — the part that turns "it moved" into "will it keep going?" — are on the member DriftLab. Read what the metrics mean in the PEAD guide.
What is an implied move?
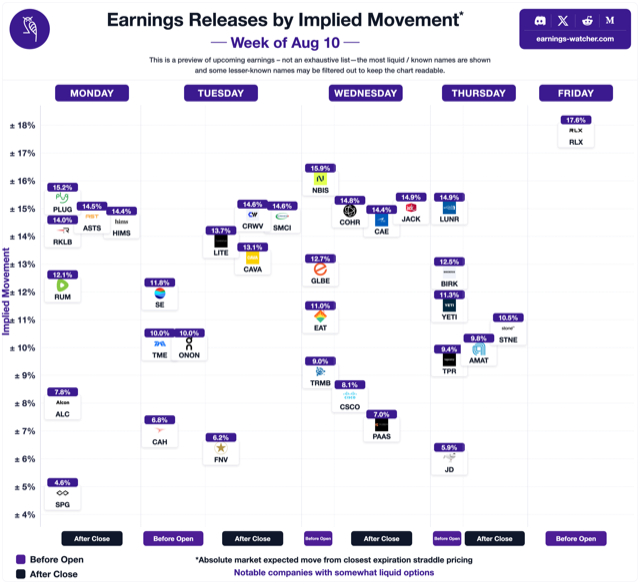
The implied move is the size of the earnings-day move the options market is pricing in, derived from the at-the-money straddle expiring just after the report. It is a market price, not a forecast. Learn more: how to calculate the implied move, or try the expected move calculator. After the report, options typically reprice sharply — the IV crush calculator shows what an option is worth once implied volatility resets.
Everything on this page is free and refreshes daily. Members get the tools that turn it into a decision.
For LYG and every stock on the calendar: beat probability against today's implied move, an IV-crush forecast for the morning after, a straddle simulator for this exact report, and the live IV-rush radar — the same data pipeline behind this page, pointed at your trades.