
What gets flagged, and why
Scanners look for three patterns. Volume far above open interest — when a contract trades multiples of its existing open interest in a day, someone new is building or unwinding a position rather than shuffling old ones. Blocks — single prints of hundreds or thousands of contracts, usually negotiated off-screen and often institutional. Sweeps — one order split across several exchanges and filled aggressively at the ask, the signature of someone who wants size now and will pay for speed. Sweeps carry the strongest urgency read, which is why flow services highlight them.
Why most of it is noise
The flag tells you a big trade happened. It does not tell you why. A fund buying 10,000 puts might be bearish — or hedging a long stock book it has no intention of selling. A "bullish sweep" might be one leg of a spread whose short legs printed elsewhere, flipping the position's real character. And without open/close data, a giant print can be someone exiting. Studies of retail flow-following consistently find the edge evaporates after spreads and timing; the sellers of the trades are not reliably dumber than the buyers.
The earnings angle: flow becomes a number
Options activity concentrates around earnings, for the obvious reason — a scheduled, binary information event. All of that repositioning pushes option prices, and therefore implied volatility, higher into the report: the IV rush. Here is the useful reframe: the net effect of every flagged and unflagged trade is already summarized in one number, the implied move — what the whole market, hedgers and speculators combined, is paying for the event. Instead of decoding a single sweep, ask the question the market has already voted on: how big a move is priced in, and does this stock's history say that pricing runs hot or cold? That comparison — implied vs actual, per report, over years — is measurable, and it is what our season tracker and per-ticker pages track continuously.
Using UOA sensibly
Where it helps: as an attention filter (why is this name suddenly active?), and as texture around a thesis you already hold. Where it hurts: as a standalone signal to copy trades whose purpose you cannot see. If a flagged name is reporting soon, ground yourself in the numbers first — the live implied move, the 10-year average move, the beat rate — then decide whether the flow story adds anything. On quiet non-event names, check whether the "unusual" print is just a roll to next month before reading meaning into it.
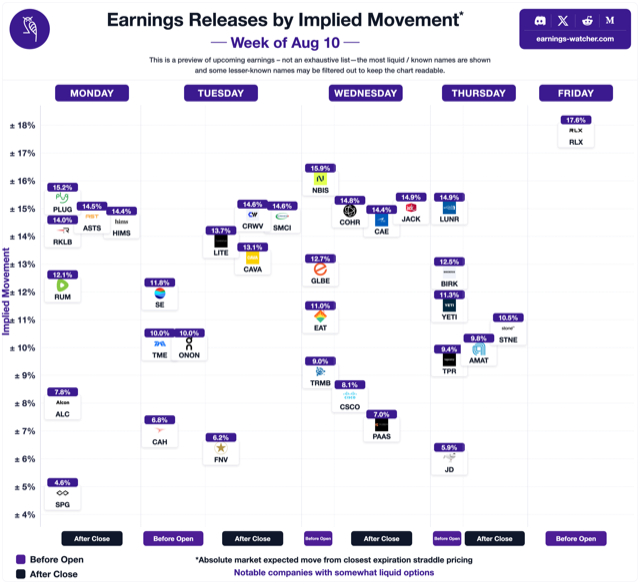
Unusual activity before an earnings report
This is where the signal is least ambiguous, because there is a scheduled reason for it. In the sessions before a confirmed report, option volume in a name reliably rises — and so does implied volatility, because the market is pricing an event it knows is coming. Both of those will light up an unusual-activity screen, and neither one tells you that somebody knows something.
The useful question is not "is there unusual volume?" but "is the priced move unusual?" That has an answer. The options market publishes its estimate of how far the stock will move, and the stock has a ten-year record of how far it actually moved. When a screen flags a name in the week before its report, the check worth running is whether the implied move is large or small relative to that history — not whether the volume looks big in isolation.
A name priced for ±4% that has averaged ±9% over its last forty reports is interesting. The same volume spike on a name priced for ±12% that has never once moved that far is interesting for the opposite reason. Volume alone cannot distinguish those two cases; the implied-versus-realised record can.
Separating signal from noise
Before treating a flagged trade as information, it is worth asking:
- Is there a scheduled catalyst? An earnings date, an investor day, a court ruling. Most "unusual" activity sits in front of something already on the calendar.
- Was it bought or sold? A screen shows size, not direction of intent. Large call volume is as consistent with someone writing calls against stock as with someone betting on a rally.
- Is it one leg of something bigger? Spreads, rolls and hedges print as separate trades. A single flagged leg can be the least meaningful part of the position.
- Is the strike reachable? Compare it against the implied move and the stock's own distribution of past earnings reactions. A strike outside the 95th percentile of ten years of moves is a lottery ticket, not a signal.
- How liquid is the contract normally? In a thin series, one ordinary institutional order is "unusual" by construction.
None of this makes flow data useless. It makes it a starting point that needs a second measurement before it means anything — and around earnings, that second measurement is the implied move against the realised record.
What EarningsWatcher publishes instead
We do not publish options flow. What we publish is the measurable half: for each covered name, the move the options market is pricing into the next report, ten years of what actually printed, and how often the realised move exceeded the implied one. The weekly card carries it for the names reporting next, the season tracker keeps the running record, and the same numbers are available as a free JSON API.
If you already use an unusual-activity screen, that is the natural companion to it: the screen tells you where people are trading, and the implied-versus-actual record tells you whether what is priced there is cheap or expensive by that stock's own standards. For the broader strategy picture, see options strategies around earnings.
Frequently asked questions
What is unusual options activity?
Option trades that break a contract's normal pattern — volume far above open interest, large blocks, or multi-exchange sweeps — flagged as potential informed positioning.
What is the difference between a sweep and a block?
A sweep is one aggressive order split across exchanges for speed; a block is a single large negotiated print. Sweeps read as urgency; blocks are more often hedges or spread legs.
Is unusual options activity a reliable buy signal?
No. Most flagged trades are hedges, rolls, or partial spreads, and without open/close data their direction is a guess. Treat it as context, not a signal.
How does it relate to earnings?
Pre-earnings repositioning is what drives the IV rush, and its net result is the implied move — a single measurable number that is easier to test against history than any individual trade.