Two earnings trades planned with an AI assistant, and what happened next
Imagine asking your AI assistant to find an earnings setup, explain the numbers behind it, price the structures, simulate the outcomes and place the paper trade, all in one conversation. That is what connecting Claude, ChatGPT or Cursor to EarningsWatcher through MCP does. In July 2026 a member did exactly that, twice: a long straddle on NFLX and a short strangle on SOFI. Here are both conversations, what the assistant pulled from our tools at each step, and how each trade ended.
Every figure in these conversations came from EarningsWatcher through the MCP connection: the live implied move, ten years of implied-versus-actual history, the option chain, the simulator with IV crush modelled, the backtester with real fills, and the paper-trading book. The assistant read the data, priced the structures and ran the numbers. The member asked the questions and made the calls. Education only, paper money throughout.
1. NFLX, July 16: “what trade setup for earnings today?”
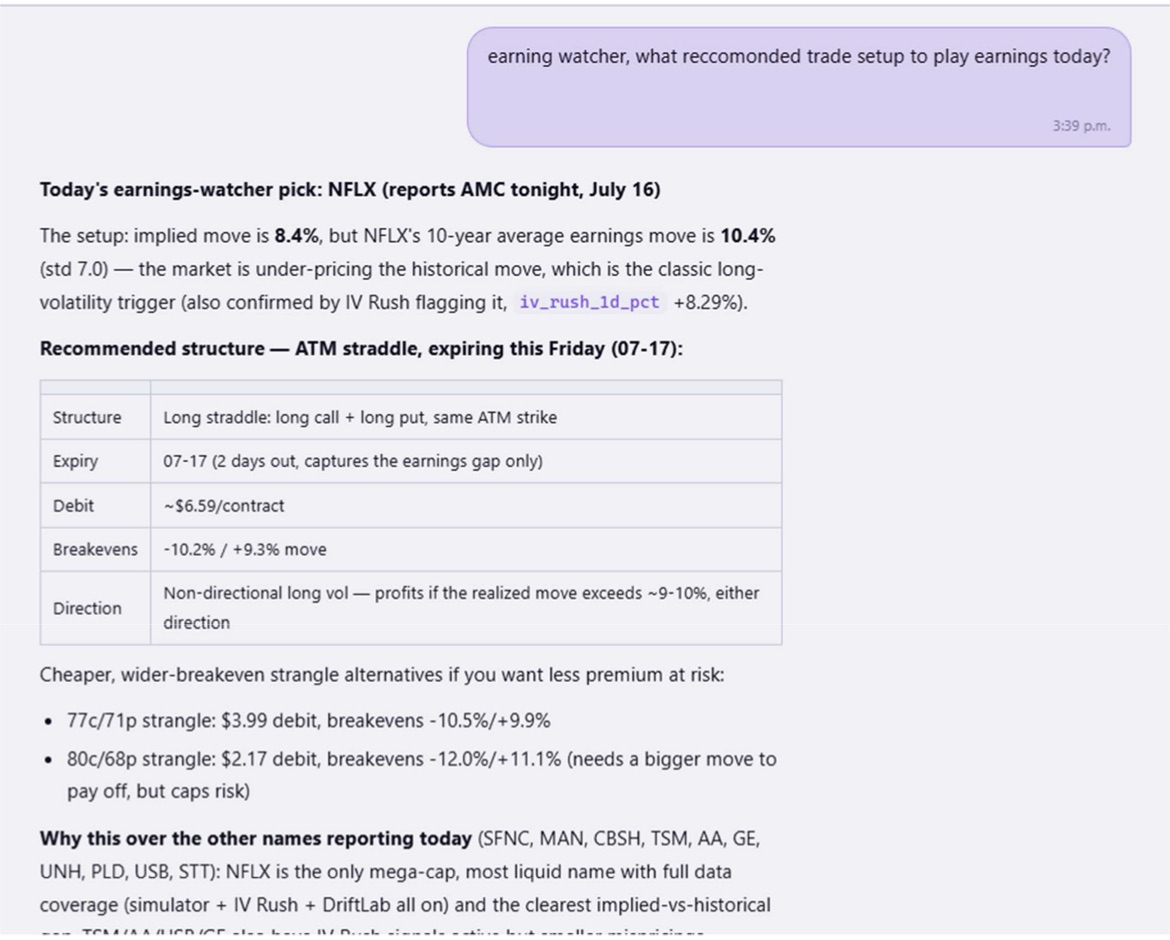
At 3:39 pm on the day Netflix reported after the close, the member asked one open question: which name to play today, and how. The assistant scanned every company reporting that day through the calendar, checked which ones had full coverage across the simulator, IV Rush and DriftLab, and came back with NFLX for one reason: a gap between what options were pricing and what the stock usually does.
Implied move is 8.4%, but NFLX's 10-year average earnings move is 10.4%. The market is under-pricing the historical move, which is the classic long-volatility trigger. IV Rush is flagging it too.
Then it priced three structures off the live option chain, expiring that Friday, with breakevens already computed:
| Structure | Debit | Breakevens | Pays if |
|---|---|---|---|
| ATM straddle | about $6.59 | −10.2% / +9.3% | the stock moves more than about 9 to 10% either way |
| 77c / 71p strangle | $3.99 | −10.5% / +9.9% | a slightly bigger move, for less premium at risk |
| 80c / 68p strangle | $2.17 | −12.0% / +11.1% | a big move; cheap, but usually expires worthless |
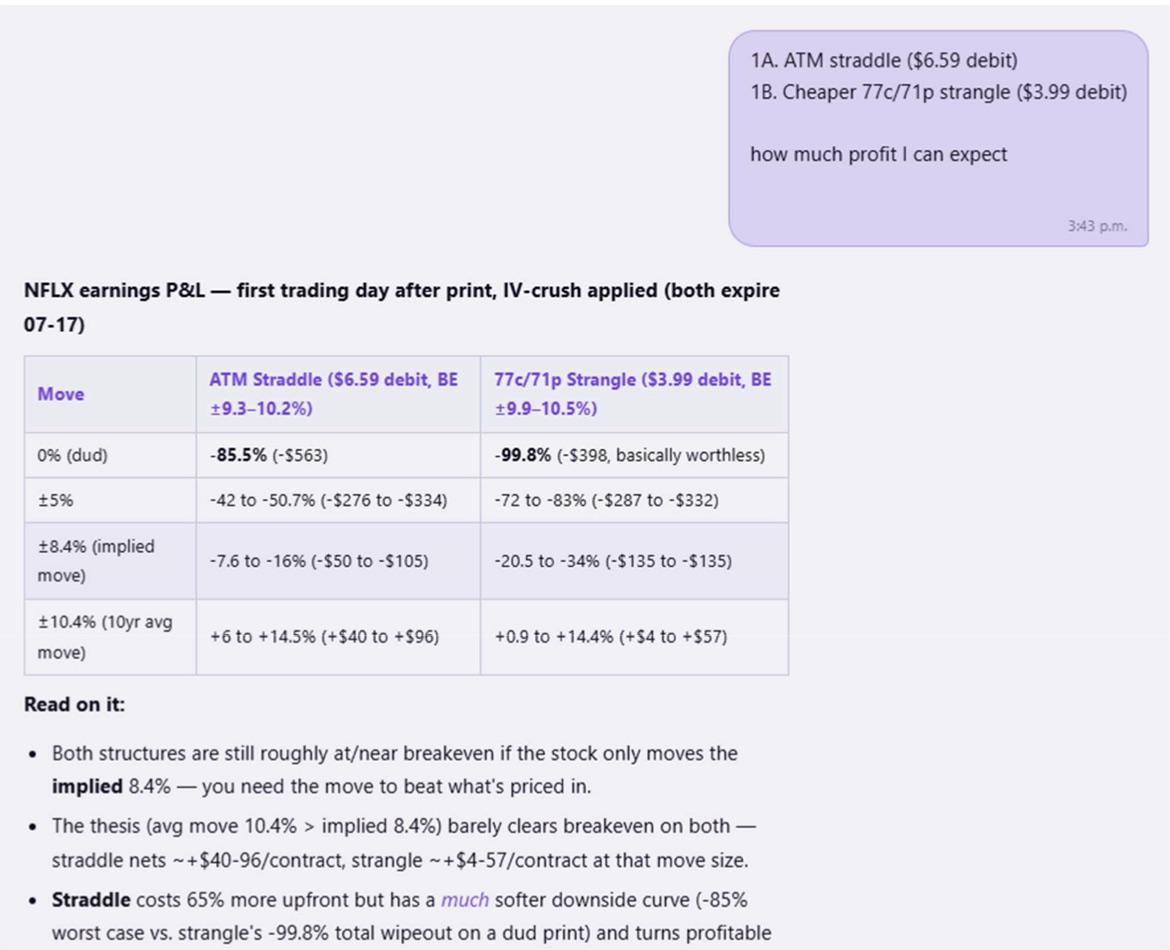
The member asked the obvious follow-up: how much profit can I expect? This is where a connected assistant earns its keep. It ran our simulator with the post-earnings IV crush applied, at four move sizes, for both structures, and answered with a P&L table instead of a promise. The line that matters:
Both structures are still roughly at breakeven if the stock only moves the implied 8.4%. You need the move to beat what is priced in. At the 10.4% average, the straddle nets about $40 to $96 per contract.
He pushed once more: backtest alternatives with better risk-to-reward. The assistant ran six structures through our backtester on real historical fills, and gave the sample-size warning before the table: the backtester held two NFLX events at the time, “two data points, not twenty.” In both, the long straddle lost 66% and 84% of its debit by the next close. The short strangle kept nearly all of its credit both times. Idea, pricing, simulation and backtest, inside ten minutes, without opening a single screen.
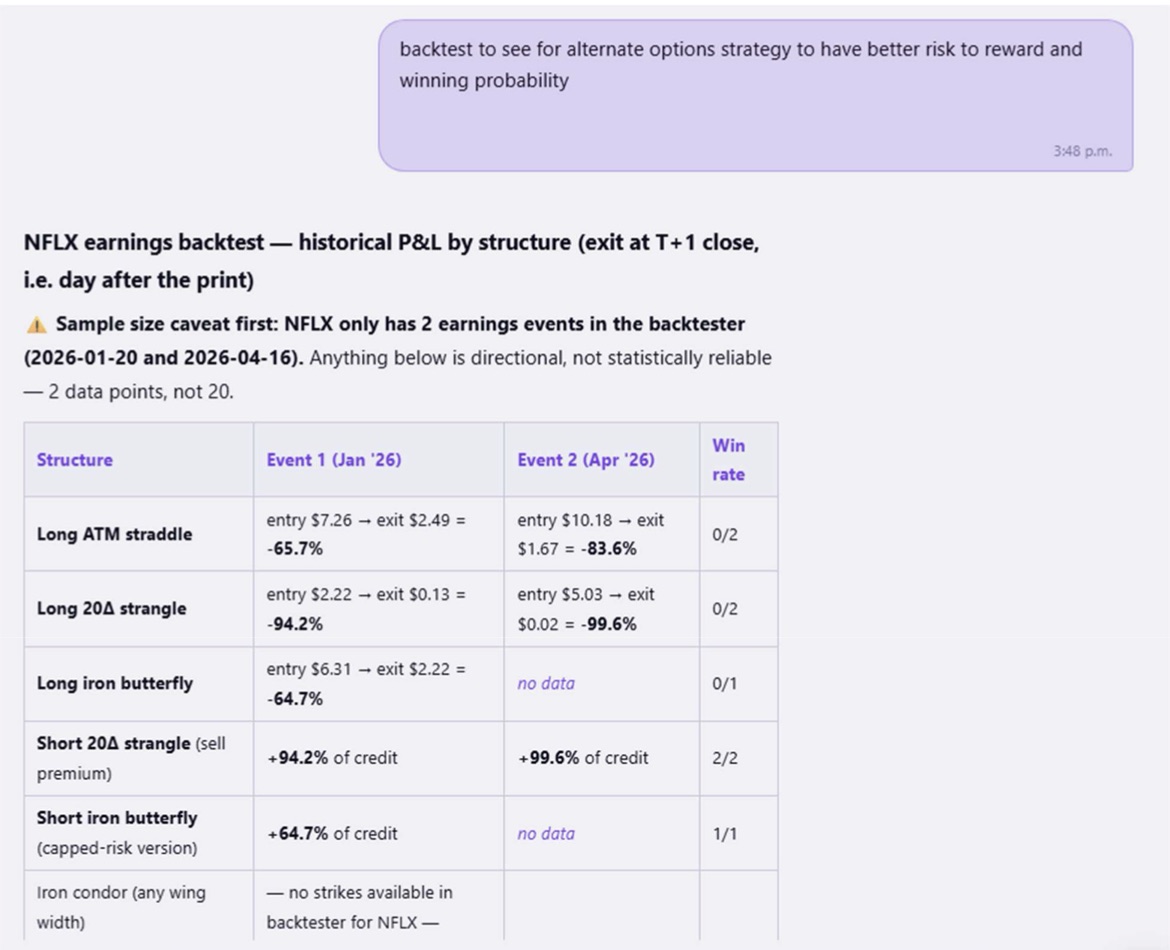
The member asked for a long-volatility trade, and the assistant, reading our data, showed him that the same trade had lost the last two times. It did not sell him the idea. It gave him the research to judge it. That is the difference between an assistant guessing from memory and one connected to real numbers.
2. What NFLX actually did
From our implied-move history for NFLX, the July 16, 2026 print:
| Measure | Value | Versus the trade |
|---|---|---|
| Implied move at the close | ±9.4% | It had risen from the 8.4% quoted at 3:39 pm. The gap the thesis relied on had half closed by the bell. |
| Peak intraday move next day | −12.5% | Beyond the straddle's −10.2% breakeven. A winner, if closed there. |
| Next-day close | −7.3% | Inside the breakeven. At the planned exit, the straddle lost roughly a fifth to a quarter of its debit, by the assistant's own P&L table. |
So the stock moved more than the historical average, and the trade still lost at the planned exit. Not every trade wins, and this one was taken with the odds on its side and the reasoning written down. The reason it lost is not bad luck. The 10.4% average that built the thesis is a peak intraday figure, the way we compute the default earnings move across the site. The P&L table was computed at the next day's close. Those are two different statistics, and NFLX split them: it went through the breakeven during the session and came back inside it by the close.
Our wider record for NFLX says the same thing, and it says it before the trade, not after. Over the 16 prints since 2022 with an implied move on file:
| Exit rule | Move beat the implied | Average absolute move |
|---|---|---|
| At the next open | 6 of 16 | 7.7% |
| At the intraday peak | 10 of 16 | 10.3% |
| At the next close | 8 of 16 | 8.0% |
| Implied move, average | 8.5% |
Over the full ten years, forty prints, the average peak move is 10.5% and the average close move is 8.2%, with a median close of 7.3%. A Netflix straddle bought at the implied move has, on average, been a small loser at the open, a small loser at the close, and a winner only at the intraday extreme. The historical data would have said to sell into the spike, and on July 16 the spike came: −12.5% against a −10.2% breakeven. The plan said close, and the close was −7.3%.
Selling at the peak is easy in a table and hard in a session: nobody rings a bell at the low. What the history supports is a target, not hindsight. Set the exit at the breakeven, or a little beyond it, and let the order work during the day rather than waiting for the close.
3. SOFI, July 29: “one idea with backtested results”
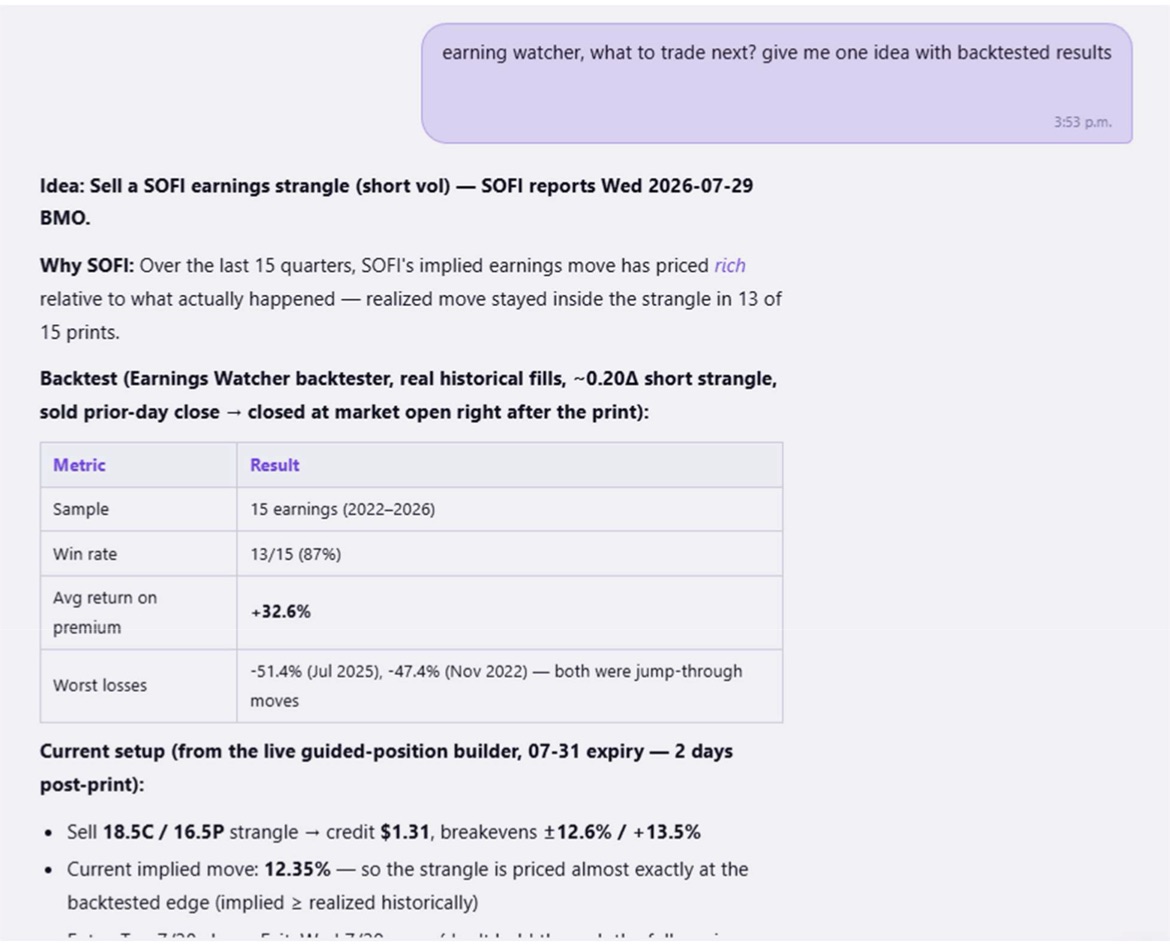
Two weeks later, a different question: what to trade next? One idea, with backtested results. No ticker given. The assistant searched the coming week's calendar, compared implied moves against realized history name by name, and went looking for the opposite edge: a company whose options habitually price more movement than the stock delivers.
Over the last 15 quarters, SOFI's implied earnings move has priced rich relative to what actually happened. The realized move stayed inside the strangle in 13 of 15 prints.
The backtest it showed used real historical fills: a short strangle at roughly 20 delta on each side, sold at the prior close, bought back at the open right after the report.
| Backtest, 15 SOFI reports (2022 to 2026) | |
|---|---|
| Win rate | 13 of 15 |
| Average return on premium | +32.6% |
| Worst two | −51.4% (July 2025) and −47.4% (November 2022), both jumps straight through a strike |
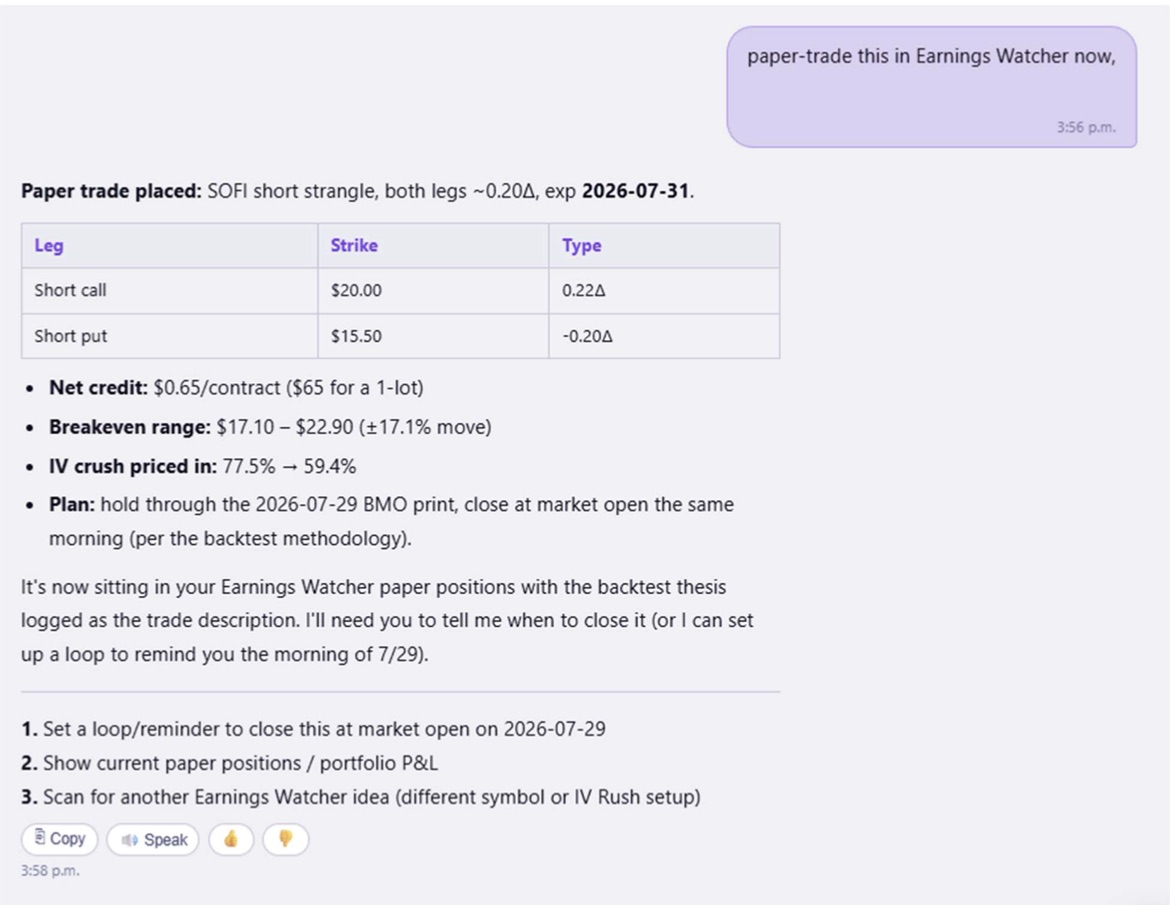
The member did not take the idea on faith, and he did not have to leave the chat to act on it. He said paper-trade this in EarningsWatcher now, and the assistant built the position from the live chain and placed it in his paper book, with the thesis written into the trade description so he could grade himself later:
| Leg | Strike | Delta |
|---|---|---|
| Short call | $20.00 | 0.22 |
| Short put | $15.50 | −0.20 |
- Net credit $0.65 per contract, breakevens $17.10 to $22.90, about ±17% from the stock.
- Implied volatility 77.5%, expected to crush to about 59% after the print.
- Plan: hold through the Wednesday pre-market report, close at the open, the same rule the backtest used.
4. What SOFI actually did
From our history for SOFI, the July 29, 2026 print:
| Measure | Value | Versus the trade |
|---|---|---|
| Open after the report | −7.4% | Well inside the ±17% range. This was the planned exit: the position was bought back with most of the credit kept. |
| Peak intraday move | −11.1% | Still inside, even for someone who ignored the plan and held through the session. |
| Close | −8.9% | Inside. |
A clean win, and a boring one, which is what a short-volatility trade is supposed to look like. Two things kept it boring. The implied move going in, about 12%, matched SOFI's average peak move of the last two years, and the closes have run well inside it. And the exit was immediate. The print before this one, in April 2026, closed −15.4% against a 10.2% implied move. The same structure, held through that session, would have been one of the backtest's losing rows.
Our record for SOFI over its last 16 prints with an implied move on file: the close stayed inside the implied range 12 times. The intraday peak stayed inside only 7 times. Sellers of SOFI premium are paid for being quick.
5. What the two conversations show
Exit where the statistic lives
The NFLX thesis was built on peak moves and cashed at the close. That mismatch, not the direction call, decided the trade. Before entering a long-volatility position, decide whether the plan is to sell into the spike or hold to a fixed time, and check the historical number for that exit. On NFLX the difference is the whole trade: a straddle at the implied breakeven has won 10 of the last 16 prints at the peak and 8 of 16 at the close. Our implied-move pages show both figures for every print, for this reason.
Two data points are a warning, not a backtest
The assistant said it, and it was right to. NFLX has a forty-print move history on our pages and only two events in the option-level backtester, because the backtester needs full historical chains and those start in 2026 for most names. When the sample is that thin, the move history is the better guide, and the backtest is a sanity check on structure, not on edge.
Rich implied plus a fast exit is the short-vol recipe
SOFI worked because both conditions held. The 13-of-15 record contains two losses of about half the credit, and the print just before this one would have been a third. A high win rate on an earnings strangle describes the exit discipline as much as the stock.
The research is the product
Neither conversation was “tell me what to buy”. It was: which name, what structure, priced how, what does the history say, and what does the simulator say if the move disappoints. Every answer came from EarningsWatcher's data in seconds, and every answer could be challenged with the next question. The member chose, papered it, and could review the result later. That is what the MCP connection is for: research you can interrogate, in the tool you already talk to. The losing trade on this page is part of that. The odds were right, the reasoning was on record, and the lesson was in the data before the trade was placed.
6. How to run the same conversation
Everything above was done in chat, with paper money, on the same tools every member has. To run it on the names on your own watchlist:
- Connect your assistant: Settings → AI Connectors (MCP) in the member dashboard, then paste the MCP URL into ChatGPT, Claude or Cursor and sign in. The MCP page has the steps.
- Ask for today's setup: “Which name reporting today has the biggest gap between implied and historical move, and what structure would capture it?”
- Make it show its P&L: “Simulate that at ±5%, at the implied move and at the historical average, IV crush applied.”
- Make it show the record: “Backtest the same structure on this name's past prints, exit at the next close, and tell me the sample size.”
- Before you take it: “Is the historical number a peak or a close? Match my exit to it.”
- Paper it: “Paper-trade this in EarningsWatcher with the thesis in the description.” It shows up in your positions and your journal.
Two more member stories: how one member turned the MCP into a personal trading OS, and the free Rewind game, where you can trade real past earnings weeks with the same data before risking anything.
Put the same research behind your own questions
Every membership includes the MCP connection: implied moves, move history, option chains, simulator, backtester, paper book and journal, in ChatGPT, Claude or Cursor.